
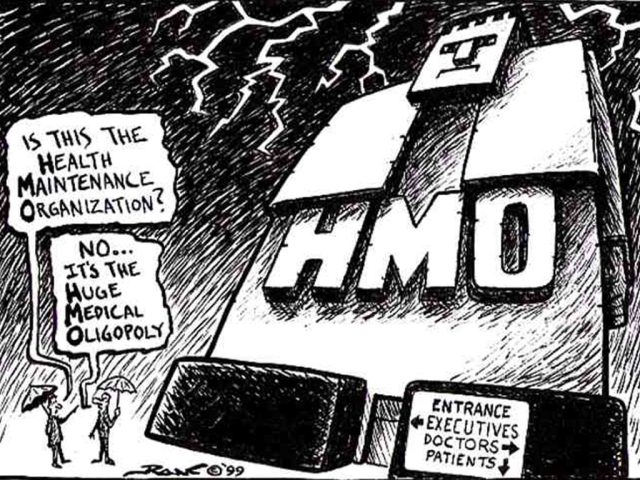
The part I hate about writing is the first paragraph — the introduction. You have to say something pithy that grabs readers’ attention and sets the tone. Sometimes the intro comes naturally; most of the time it doesn’t. I wanted to write an article about health maintenance organizations, but after staring at the computer screen for a few hours I still didn’t have an intro. I was about to give up when it occurred to me to stick to my contrarian roots and write an article without one.
So here goes.
HMOs appear to be perfect stocks for today’s market. They have good balance sheets, terrific free cash flows and recurring, highly economics-insensitive revenues. The global macro stuff doesn’t really affect them. Greece could be abducted by aliens, Spain could go to war with Finland, and we’d all still be getting sick and buying health insurance. Rising unemployment and underemployment might put a small hole in my rosy thesis, but no worries: With 10,000 baby boomers signing up for Medicare every day and expected to do so for the next decade, that hole will patch easily.
What intrigues me the most about these companies is that they are misunderstood by investors. Though we call them health insurers, they are not really insurance companies, at least not in the true sense of the term. Yes, they take premiums up front and pay out medical costs over time, but they are actually health care logistics companies — they pass on health care costs to their customers. They are only insurance companies if an investor’s time horizon is a few quarters, because once in a while they’ll misprice the risk and their profitability will stutter. However, since they reprice their business every 12 months, the mispricing will be fixed at the next renewal. Even in their worst years, HMOs still make a lot of money.
During the 1990s, HMOs tried very hard to manage rising costs, even as their reputation was undermined (in John Grisham’s 1995 bestseller The Rainmaker, an insurance company played the villain). Since then the industry has gone through a transformational consolidation that has helped it to achieve significant economies of scale and more-rational (less competitive) pricing. HMOs stopped fighting rising health care costs and embraced them; they just pass them on, dollar for dollar, to the customer. In fact, they woke up to this little realization: Health care inflation is their friend — it drives revenues and thus profitability.
It is also assumed that there is a constant political risk with HMOs. True, politicians love to hate HMOs, especially in their speeches and presidential debates. You pick up a lot more voters when you go after “evil” HMOs than when you embrace them as the most cost-effective alternative. Despite all the negative rhetoric being spit out by spineless politicians, HMOs are not going anywhere. They are deeply integrated into our health care system — they are our health care system.
And here is the most ironic part: Even if political rhetoric in the pursuit of cost savings spilled over into fierce action, and HMOs were euthanized and their profits were nationalized, the U.S. would save only about $13 billion a year (the total profitability of the HMO industry). Though it sounds like a fair chunk of change, that’s only 0.6 percent of our total $2.2 trillion in health care costs, or a few months of health care inflation. And to provide logistical health care services, the government would have to make a sizable investment (probably over $100 billion) and take over administration of health care. The $13 billion that HMOs currently earn would look like a promised land that the government would never reach.
Let’s face it, government is good at doing some things, like running courts and the military. But due to misaligned incentives and inherent bureaucracy, government will never be as efficient as for-profit enterprises. This is why the U.S. prospered and the Soviet Union disintegrated.
In the first two years of the Obama presidency, HMOs faced uncertainty as to whether Obamacare would even let them survive. Now that the impact of Obamacare on HMOs is for the most part known and uncertainty has turned into certainty, the companies will enjoy an influx of customers, courtesy of the U.S. taxpayer, but with them will come lower margins. Net-net, Obamacare should not have a significant impact on their business. But HMOs are priced as if the Obamacare outcome were still uncertain — they sport single-digit price-earnings ratios on earnings that are continuing to rise and that have grown into the mid-teens over the past decade.
Since I started this article without an introduction, I’ll finish without a conclusion — or at least without recommending any specific companies, as the entire HMO industry looks attractive.
P.S. In the musical note section I want to share with you Franz Liszt’s Piano Concerto No. 1, performed by Lang Lang. As one of my favorite childhood memories, I remember walking home with my father on a sunny Sunday afternoon. I was maybe nine years old. There was the sound of classical music coming from the fourth-floor window of our apartment building. Our neighbor was listening to music very loud. My father said with admiration, “She is listening to Liszt.” This was the first time I had heard of Franz Liszt. I remember father explaining to me the “z” in his name and it was spelled differently from list, which in Russian means “leaf.” I don’t remember the music, but I do remember a certain respect in my father’s voice for the neighbor and her preference in music.


comments
0