
A note before we start: this piece began as part of the Fall Letter I sent to IMA clients last week. The rest of that letter dealt with our individual holdings, which is not something I write about publicly. But the section on AI stocks and the pandemic kept growing as I wrote it, and I think it deserves a wider audience. I have lightly edited it for readers who are not clients. Everything else is as I wrote it.
The AI Hangover Is Coming. The Pandemic Already Showed Us How It Ends.
Financial pundits looking for an analogy for what is about to happen to AI stocks reach back decades, to the 1999 dot-com bubble or the 2008 financial crisis. I have done it myself in past letters. Both offer lessons, but both are fading. Anyone under 40 was a kid in 1999, and 2008 is nearly two decades in the rearview mirror. The further we get from a crash, the harder it is to relate to it.
We don’t have to go decades back to find an analogy. Just look back a few years, to the pandemic. We all lived through it, most of us in sweatpants. And it offers a near-perfect preview of what is about to happen in AI.
The pandemic changed supply and demand for many goods and services. Supply chain constraints limited supply, lockdowns skewed spending patterns, and a temporary injection of government cash changed demand. As an analyst, it was fascinating to watch how these forces impacted businesses. Many pandemic darlings woke up with a hangover they are still nursing today.
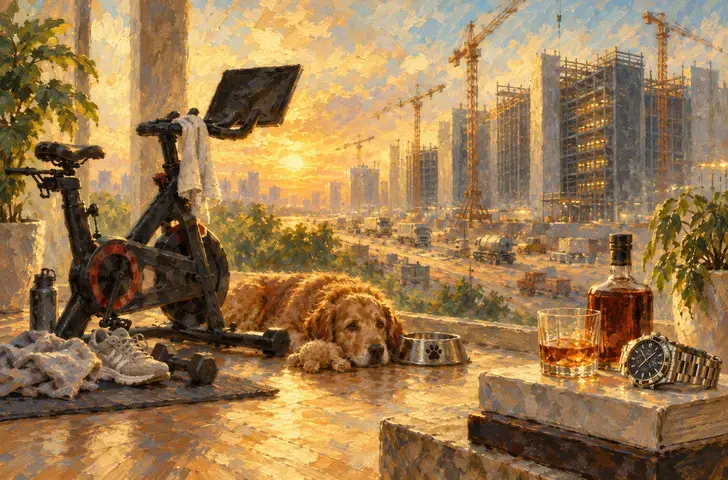
If I had to sum up the pandemic hangover in one company, the one almost every reader can relate to, it would be Peloton. A locked-down population decided, all at once, that it wanted to get in shape, and it couldn’t leave the house. Peloton was the best alternative, and demand for its bikes surged severalfold. The company could not keep up. At one point it spent $100 million just on air freight to get bikes to customers faster. So it bought a fitness equipment manufacturer, Precor, for $420 million, and committed $400 million to build its own factory in Ohio. All of this raised its operating costs substantially. And then… the economy opened up.
People canceled their memberships, and demand dried up. The company found that its costs were much higher, while the temporary spike in demand had stolen its future sales. Everyone who was ever going to buy a $2,000 bike had already bought one. The factory was never finished; it was written off. At the height of demand, management made many suboptimal decisions to satisfy customers. Today the customers are gone, but the decisions, including the debt, remain. The stock fell from $160 to single digits.
Peloton is the extreme case, but milder versions played out everywhere.
Spirits: locked-up folks, given a choice between water and booze, chose booze. Alcohol sales went through the roof, the industry increased capacity and raised prices. Demand normalized but capacity stayed.
Watches: Swiss watchmakers raised prices too much during the boom, and the same applies to many other luxury goods. The problem with luxury goods is that you can only raise prices, you cannot lower them; discounting kills the perception of what you sell.
Pets: people felt lonely, and you had a mini boom in pets. Companies like Zoetis, the largest maker of pet medicine and vaccines, went to the moon. Then pet spending normalized, and Zoetis crashed back to earth.
The list of companies and industries nursing a pandemic hangover is long. That is a bad thing for investors who bought in during the euphoria, but a good thing for value investors willing to look through the rubble.
The same will happen in AI. Today the demand is insatiable, and nobody knows how long it will last. Everything that goes into data centers, from cement, to the labor that builds them, to the electricity that runs them, to the chips that provide their intelligence, is overpriced by a large factor. Gas turbines are on track to triple in price from 2019 levels. An electrician wiring a data center makes about double what electricians make everywhere else. Nvidia sells its chips at a 75% gross margin, as if it were a software company.
Just like during the pandemic, the companies making these investments are drawing straight lines into the future. It is easy to criticize the managers who overbuilt during the pandemic, but they were making the best decisions they could with a clouded crystal ball in unprecedented times. What makes the game close to impossible is that executives are judged, and their jobs depend, on quarterly performance. Imagine Johnnie Walker sales are going through the roof in January while Jack Daniel’s sales lag. The Jack Daniel’s team had better announce a multibillion-dollar distillery on the March earnings call, or start updating their résumés. Short-term pressure leads to long-term decisions that create overcapacity.
There is an even more inconvenient wrinkle. Suppose Jack Daniel’s management stays disciplined and doesn’t expand. It avoids overcapacity of its own, but the industry is still flooded thanks to Johnnie Walker and the rest. Your own rational, long-term decisions may not save you from the decisions of others. You live and die with industry dynamics.
That is exactly the position of every company in the AI race today. No CEO wants to be the one who underbuilt. Nobody gets fired for overbuilding, at least not right away.
The counterargument is that the pandemic was temporary, while we’ll be using more AI in ten years, not less. True. But the road to “more” is not linear, and the consequences of today’s decisions are highly path-dependent. Is there a real chance we overbuild data centers? The probability is not zero; it is actually high. If demand doesn’t match the straight lines, we’ll see Peloton-times-a-thousand write-downs, and then the debt will come to collect.
And this brings me back to 1999 after all. The analogy may be fading, but one of its lessons still holds: being right about the technology does not save the investors. We use the internet tens of thousands of times more today than we did in 1999, yet telecom went through a decade-long nuclear winter. New companies emerged from it to carry the internet torch.
It is hard to imagine today, but the companies leading the market may not be the ones that ultimately reap the economic rewards of AI. They may actually fall victim to it. They are the ones writing the hundred-billion-dollar checks, often spending three dollars on AI infrastructure for every dollar of AI revenue they may eventually produce. Google had barely been born and was a nobody in 1999. Yahoo!, the 1999 king, is now a trivia question. Today’s front-runners may meet Yahoo!’s fate.
AI can change the world, and many of today’s AI investments can still turn out to be terrible. Those two statements aren’t contradictory.
The stock market isn’t pricing in that possibility. As I have written before, we live in a K economy and a K stock market. Any part of the economy that touches AI is going gangbusters; everything else is barely keeping its head above water.
You can see it in the numbers. The S&P 500 sits within about 1% of its high, so on the surface everything looks wonderful. But the median stock in the index is 17% below its 52-week high, and about two out of every five are down more than 20%, which is bear market territory. Even inside the technology sector, the median stock is down 23% from its high. A handful of AI giants are carrying the index on their backs, while the typical stock is having a pretty miserable year.
This is why our portfolios look nothing like “the market” right now, and why our returns this year look nothing like the index either, in both directions over the course of the year. Valuations don’t matter until they do, and then years of gains vanish in days or weeks. We are investing not for the next quarter or the next year but for a decade out. I am not joining the peloton of insanity just to win a battle (a quarter) and lose the war.
I don’t usually do this, but given what is happening in the market right now, I figured I’d share a few of my other pieces that relate to it:
- Today’s Market = 1999 Capex + 2008 Credit
- This Is Your Captain Speaking: Buckle Up
- Narrative Change (part 1)
- Depressing Reasons Why I Am Bullish On Gold (part 2)
Key takeaways
- The pandemic is the better analogy. 1999 and 2008 are fading from memory. The pandemic boom and hangover, with Peloton as the extreme case and spirits, watches, and pets as milder ones, shows how a temporary demand surge leads to overbuilding.
- Everything feeding AI data centers is overpriced. Gas turbines are headed to 3x their 2019 prices, data-center electricians earn about double, and Nvidia sells chips at a 75% gross margin.
- Quarterly pressure drives overcapacity. No CEO wants to be the one who underbuilt. Even disciplined companies can’t escape an industry their competitors flooded.
- Being right about the technology doesn’t save the investors. The internet won, but telecom endured a decade-long winter, and Yahoo! became a trivia question. Today’s AI leaders, spending about $3 on infrastructure per $1 of eventual AI revenue, may meet the same fate.
- The index hides a K-shaped market. The S&P 500 is within about 1% of its high, but the median stock is 17% off its 52-week high and roughly 40% are down more than 20%. IMA invests for a decade out, not the next quarter.


comments
0